By Evan Kowalski · Editor
Published
Answer in brief
An at-fault accident typically affects your car insurance rates for three to five years, depending on your insurer's lookback period and state rating regulations. During this time, insurers apply an underwriting surcharge that increases your premium before gradually declining as the incident ages. You can offset this premium increase by adjusting deductibles, maintaining clean driving habits, and shopping quotes across carriers with differing surcharge schedules.
The Insurance Lookback Period Explained
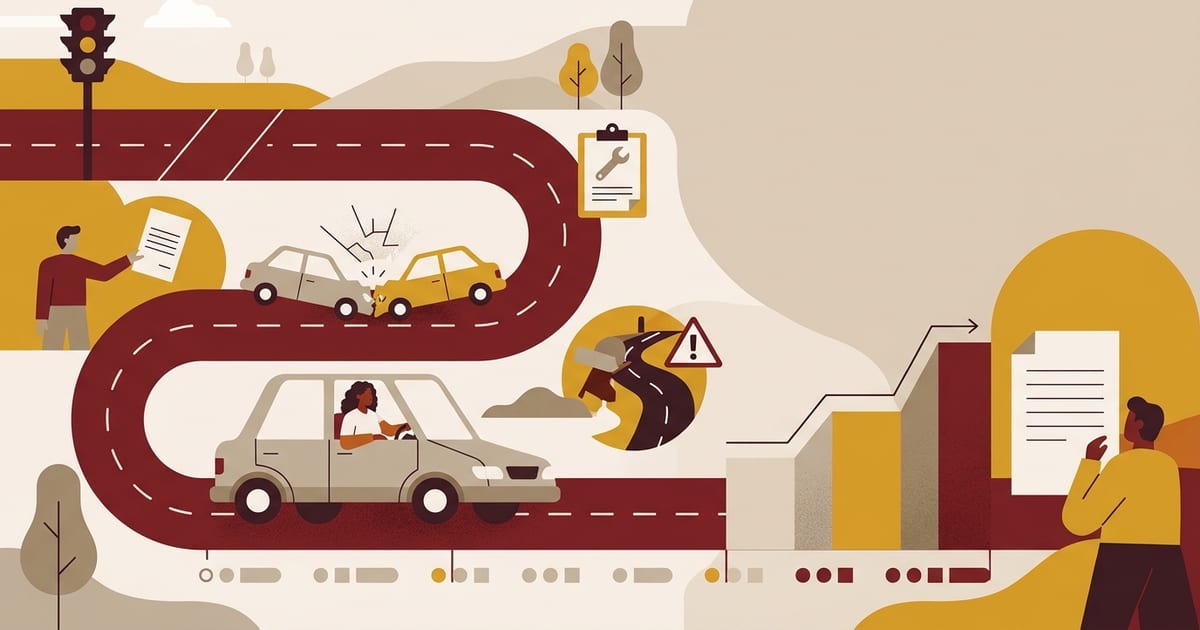
When you apply for a new policy or renew an existing one, insurance carriers run your motor vehicle report and claims history through industry databases. The timeframe underwriters review is called the lookback period. For most standard insurance companies, this window spans roughly 36 to 60 months (three to five years) from the date of the incident.
An at-fault accident on your record signals increased loss probability to underwriters. Rising repair costs, advanced vehicle electronics, and medical expenses have made claim settlements significantly more expensive across the country. Consequently, insurers use actuarial schedules to add a direct surcharge to the policy's liability, collision, and medical coverages, driving up your total annual premium.
How State Regulations Shape Accident Penalties
How long and how severely an accident impacts your rate depends heavily on state insurance law. State insurance departments approve company rate filings and establish strict guidelines on which incidents can trigger surcharges.
For example, California Insurance Code § 1861.02 mandates that auto insurance rates must be determined primarily by three mandatory factors: the insured's driving safety record, annual miles driven, and years of driving experience. California law also guarantees that qualifying motorists receive a Good Driver Discount of at least 20% below the rate otherwise charged. A major at-fault crash can disqualify a motorist from this statutorily protected discount, creating a steep financial impact.
| Policy Year Following Crash | Underwriting Surcharge Level | Market Options & Impact |
|---|---|---|
| Year 1 (Months 1–12) | Maximum Surcharge (Peak Impact) | Preferred discounts removed; tier reclassification common. |
| Year 2 (Months 13–24) | Moderate Surcharge (Step-Down) | Surcharge may decrease slightly with demonstrated clean driving. |
| Year 3 (Months 25–36) | Reduced Surcharge | Approaching end of lookback window for many regional carriers. |
| Year 4–5 (Months 37–60) | Minimal or Fully Removed | Clean record restores preferred-tier eligibility with standard insurers. |
How Insurers Calculate Surcharges
Insurers do not treat all collisions identically. In their regulatory rate filings, companies establish specific monetary thresholds and fault determinations before levying a penalty. Typically, a collision must involve at least 50% driver fault and exceed a minimum dollar threshold in property damage or bodily injury payout before triggering an underwriting surcharge.
Minor parking mishaps with negligible repair bills may result in zero surcharge, whereas crashes involving personal injury or high-value physical damage carry significant premium penalties. HLDI loss data shows that vehicle claim severity varies widely by weight, build, and replacement part complexity. Surcharges are calculated as a percentage multiplier applied directly to your baseline risk rate, meaning drivers in higher baseline areas or age groups experience larger dollar increases.
Steps to Lower Your Insurance Premium After a Crash
You do not need to passively accept inflated rates for three to five years. Taking targeted measures helps control overall costs while waiting for an incident to roll off your lookback window:
- 1
Adjust Physical Damage Deductibles
Increasing your collision and comprehensive deductible from $200 to $500 can cut your physical damage premium by 15% to 30%, while moving to a $1,000 deductible can save 40% or more on those coverages.
- 2
Complete an Approved Defensive Driving Course
Many states allow motorists to offset point penalties or qualify for an insurer-sponsored safety discount by completing an accredited driver improvement curriculum.
- 3
Combine Multiple Policies
Utilize bundling discounts by pairing your auto policy with homeowners, condo, or renters coverage to secure double-digit percentage credits across policies.
- 4
Re-evaluate Older Vehicles
If you drive an older automobile with a market value less than ten times the annual physical damage premium, consider dropping collision and comprehensive coverages altogether.
- 5
Shop Quotes Annually
Because surcharge percentage scales step down annually and carriers evaluate historical claims differently, shopping at each twelve-month mark ensures you capture rate reductions as soon as they become available.
When to Switch Insurers After an Accident
Many drivers assume that shopping for coverage immediately after an accident is counterproductive. However, remaining with your incumbent carrier after a substantial rate increase is rarely the most economical choice. While one carrier might increase rates by 40% for an at-fault loss, a competing carrier might apply a flat 20% surcharge or maintain a shorter lookback schedule.
According to the National Association of Insurance Commissioners, the countrywide average expenditure for auto insurance reached $1,281 in 2023, reflecting a 13.98% single-year rise driven by broader inflationary pressures. When an accident surcharge is layered on top of broader rate adjustments, comparing multiple options using our quote comparison tool is the most reliable way to find which carrier offers the best rate for your specific record.
Questions & answers
Does a non-fault accident raise car insurance rates?
In general, a not-at-fault collision does not incur an underwriting surcharge. However, frequent comprehensive or non-fault claims in a brief window can sometimes impact tier placement or eliminate zero-claim discounts depending on carrier guidelines.
Can an insurer cancel my policy immediately after an accident?
Insurers generally cannot cancel an active policy mid-term due to a crash unless there was material misrepresentation or fraud. However, they can issue a notice of non-renewal when your policy term reaches its expiration date.
How do I know when an accident has fallen off my record?
You can request a copy of your motor vehicle report from your state licensing agency or review your consumer claims report. Once the incident passes the 36-to-60 month window defined in your insurer's rate manual, the surcharge must be dropped.
Will accident forgiveness prevent my premium from increasing?
If your policy includes an accident forgiveness endorsement and you met the qualifying conditions prior to the crash, your carrier will waive the surcharge for your first eligible incident. However, that incident will still be visible to other insurers if you shop around.
Terms: Lookback period, At-fault accident, Surcharge, Rate filing, Collision coverage
Sources and references
Legal figures on this page (minimum limits, filing periods, statutory benefits) are checked against the primary law or the state insurance regulator listed below. Links and figures last verified Nov 2026.
- Insurance Code § 1861.02 — rating factors and Good Driver Discount — California Legislative Information, Cal. Ins. Code § 1861.02Primary lawRates must be determined by, in decreasing order of importance, driving safety record, annual miles driven and years of driving experience; optional factors may follow. Good Driver Discount policies must be at least 20% below the rate otherwise charged.
- Trends and Insights: Auto insurance rates (June 2024) — Insurance Information Institute (2024)Independent researchWhy premiums rose 2021–2024: crash frequency and severity, repair and labour inflation, vehicle technology, attorney involvement.
- Insurance losses by make and model — Highway Loss Data InstituteStatistical dataRelative claim frequency and severity by vehicle under collision, property damage, comprehensive, PIP, MedPay and bodily injury coverages.
- 2019–2023 Auto Insurance Database: average premium supplement — National Association of Insurance Commissioners (2025)Statistical dataCountrywide average expenditure $1,281 in 2023 (+13.98%); combined average premium $1,438; state tables for liability, collision and comprehensive.
- Facts + Statistics: Highway safety — Insurance Information InstituteStatistical dataCrash, injury and fatality trends used to explain why liability and injury coverages cost what they do.
- Nine ways to lower your auto insurance costs — Insurance Information InstituteConsumer guidanceShop at least three quotes; raising a deductible from $200 to $500 can cut collision/comprehensive cost 15–30%, $1,000 can save 40%+; drop physical damage on cars worth under 10× the premium; bundling, low-mileage and good-student discounts.
- How to file an auto insurance claim — Insurance Information InstituteConsumer guidanceSteps after a crash: document the scene, notify the insurer promptly, understand the adjuster's role.
- What determines the price of an auto insurance policy? — Insurance Information InstituteConsumer guidanceRating factors: driving record, mileage, location, age, gender, vehicle, credit-based insurance score, coverage choices. Notes ZIP-code rating is prohibited in California and Michigan and gender rating is prohibited in seven states.
Practical guidance on this page is original editorial work. Cited sources support factual statements and do not endorse this site. Dollar ranges described as typical or illustrative are editorial estimates, not figures from these sources.