By Naomi Feld · Research Writer
Published · Updated
Answer in brief
Switch when a quote for identical coverage from a reputable insurer is meaningfully lower—most people use 10–15% as the threshold—and the new company's claims reputation and fees check out. The best moments are any renewal, after a no-reason increase, when a surcharge expires, after a move, a new car, a marriage, or a credit improvement. Loyalty discounts rarely offset the gap that builds up over several years with one insurer. Switching mid-term is allowed; you receive a pro-rated refund, sometimes minus a small fee.
The triggers
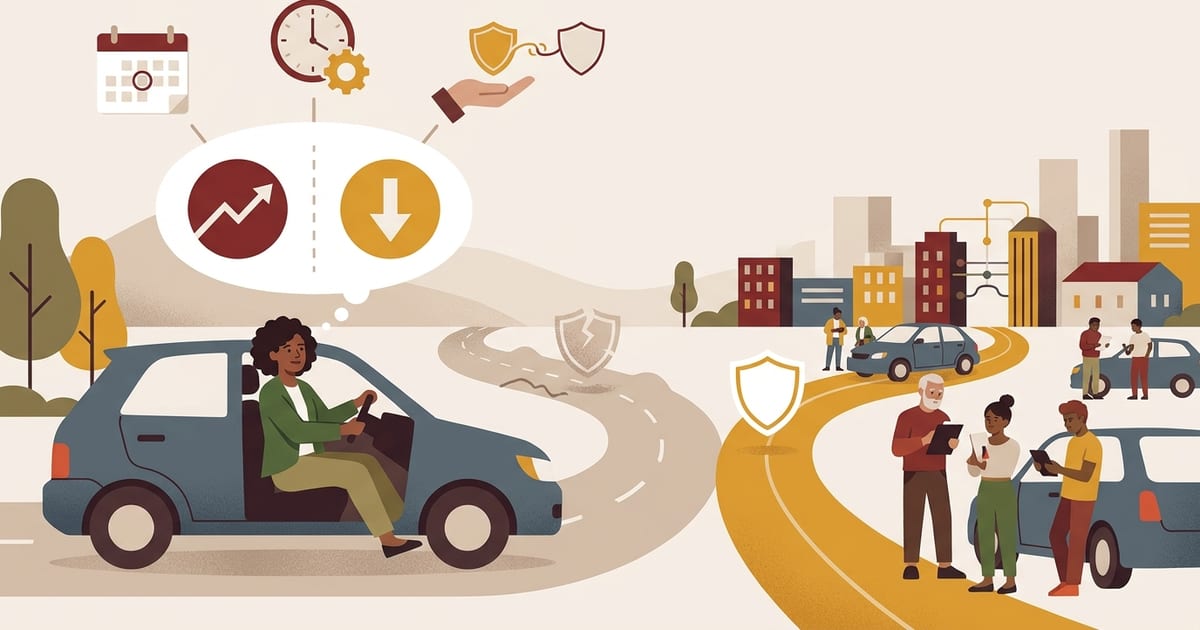
- A renewal increase you cannot explain—see why rates went up with no claims.
- A surcharge or inexperience factor about to expire; insurers with shorter lookbacks drop it sooner.
- Moving, buying a car, getting married, adding or removing a driver.
- A credit score that has improved substantially.
- Being with the same insurer for more than three years without comparing.
How to compare fairly
Use your current declarations page as the template: same limits, deductibles, drivers, vehicles and address. Get three to five quotes the same day. Add fees. Check the new insurer's complaint record with your state regulator's public data and its financial strength rating.
Switching mid-term
You can cancel at any time. The old insurer refunds unused premium pro-rata; a few charge a small cancellation fee or use a short-rate table—ask. The new policy must start on or before the cancellation date to avoid a lapse.
What loyalty is worth
Longevity discounts are typically a few percent. Meanwhile, rate differences between insurers for the same driver commonly run 20–40%. Loyalty is worth keeping only when your current insurer is also competitive on price.
Questions & answers
Is there a penalty for switching car insurance mid-term?
Usually a pro-rated refund with no penalty; some insurers charge a small fee. Ask before cancelling.
How often should I compare car insurance?
At every renewal and after any major life or rating change.
Does switching hurt my insurance history?
No, as long as there is no gap between policies.
Terms used in this guide
- Pro-rata refund
- A refund of unused premium when you cancel mid-term, proportional to the days remaining.
- Declarations page
- The summary page of a policy: insureds, vehicles, coverages, limits, deductibles, discounts and premium.
- Continuous coverage
- An unbroken insurance history. Lapses are surcharged; continuity earns discounts.
Sources and references
Legal figures on this page (minimum limits, filing periods, statutory benefits) are checked against the primary law or the state insurance regulator listed below. Links and figures last verified Nov 2026.
- Trends and Insights: Auto insurance rates (June 2024) — Insurance Information Institute (2024)Independent researchWhy premiums rose 2021–2024: crash frequency and severity, repair and labour inflation, vehicle technology, attorney involvement.
- 2019–2023 Auto Insurance Database: average premium supplement — National Association of Insurance Commissioners (2025)Statistical dataCountrywide average expenditure $1,281 in 2023 (+13.98%); combined average premium $1,438; state tables for liability, collision and comprehensive.
- Facts + Statistics: Auto insurance — Insurance Information Institute (2025)Statistical dataNAIC countrywide average auto expenditure: $1,127 (2022), $1,282 (2023); most expensive states in 2023 were Florida, Louisiana and New York.
- Nine ways to lower your auto insurance costs — Insurance Information InstituteConsumer guidanceShop at least three quotes; raising a deductible from $200 to $500 can cut collision/comprehensive cost 15–30%, $1,000 can save 40%+; drop physical damage on cars worth under 10× the premium; bundling, low-mileage and good-student discounts.
- Insurance research and advocacy — Consumer Federation of AmericaConsumer guidanceConsumer-side research on auto insurance pricing, non-driving rating factors and affordability.
- Consumer insurance information — National Association of Insurance CommissionersConsumer guidancePlain-language guides from the body of state insurance regulators; links to every state's insurance department and complaint process.
- What determines the price of an auto insurance policy? — Insurance Information InstituteConsumer guidanceRating factors: driving record, mileage, location, age, gender, vehicle, credit-based insurance score, coverage choices. Notes ZIP-code rating is prohibited in California and Michigan and gender rating is prohibited in seven states.
- Car insurance — Consumer ReportsConsumer guidanceIndependent testing organisation's guides to comparing policies and insurers.
Practical guidance on this page is original editorial work. Cited sources support factual statements and do not endorse this site. Dollar ranges described as typical or illustrative are editorial estimates, not figures from these sources.
Guide
How to Lower Car Insurance That Is Too High
A prioritised list of actions that lower a high premium—comparing, coverage changes, deductibles, telematics, discounts, vehicle and mileage—with realistic savings.
Guide
Why Car Insurance Went Up With No Claims or Tickets
The reasons a premium rises when your record is clean: base-rate increases, territory re-rating, lost discounts, age-band changes, credit shifts and vehicle symbol updates.
Guide
How a Coverage Lapse Raises Car Insurance Rates
Why a gap in coverage—even a short one—raises premiums, how insurers treat no prior insurance, and how to restart without overpaying.