By Evan Kowalski · Editor
Published
Answer in brief
Adding a teen driver to a family auto policy routinely causes premiums to surge because statistical crash involvement is highest among new drivers. Insurers classify young drivers in a high-risk rating tier due to elevated fatal crash rates and zero driving track record rather than individual character. You can offset this price increase by assigning your teen to a safe vehicle, claiming student discounts, adjusting deductibles, and comparing quotes across multiple insurance carriers.
Why Car Insurance Premiums Surge When Adding a Teen Driver
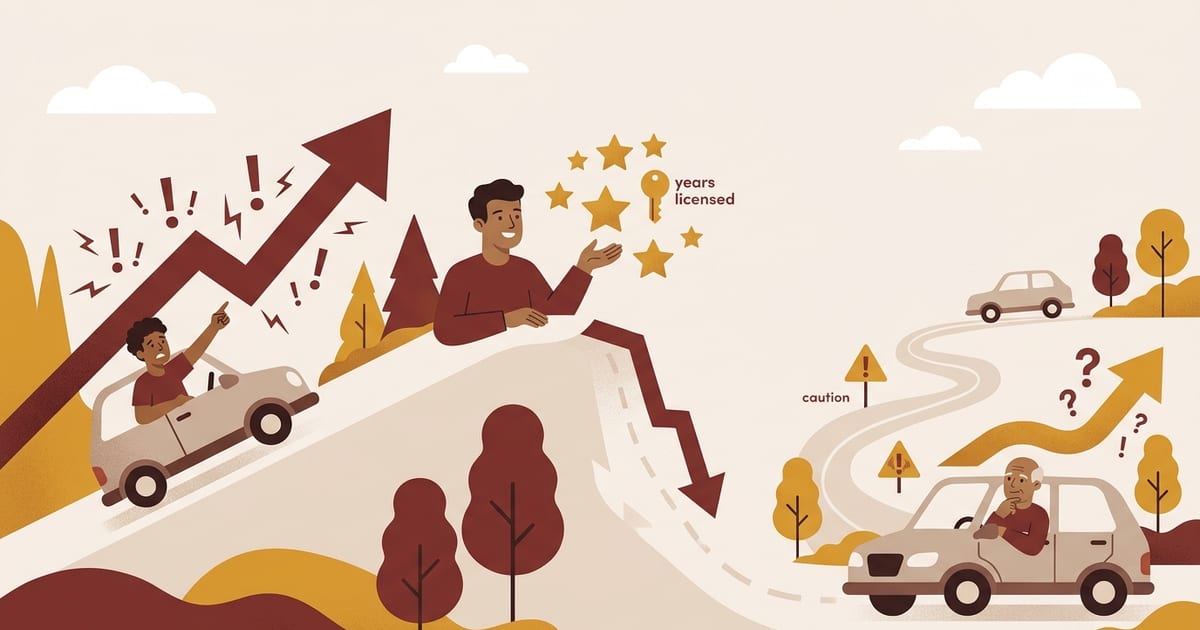
When a household policyholder contacts their insurance provider to add a newly licensed 16- or 17-year-old, the resulting premium adjustment is often jarring. Auto insurance pricing is fundamentally an exercise in risk pooling, and data consistently proves that inexperienced drivers represent the highest claim frequency and claim severity of any demographic group on American roadways. Insurers place newly licensed teens into an inexperienced operator category within their specific age band, which directly increases the base premium across bodily injury, property damage, and collision coverages.
According to research from the Insurance Institute for Highway Safety, the fatal crash rate per mile driven for 16- to 19-year-olds is just over three times the rate for drivers aged 20 and older, with the crash rate across all severity levels running more than four times higher. Crash risk is particularly acute at ages 16 and 17. The Insurance Information Institute reports that fatal-crash involvement in 2023 reached 42.40 per 100,000 licensed drivers for the 16-to-20 age group—the highest rate of any age cohort. Understanding these actuarial realities helps explain why age and experience influence premiums so dramatically.
| Age Band | Fatal-Crash Involvement per 100,000 Licensed Drivers (2023) | Relative Actuarial Risk Category |
|---|---|---|
| 16–20 | 42.40 | Highest risk group nationwide |
| 21–24 | 35.34 | Substantially elevated risk |
| 25–34 | 28.97 | Moderate-to-high risk tier |
| 35–44 | 24.18 | Average baseline risk |
| 45–54 | 21.70 | Lower-than-average risk |
| 55–64 | 19.45 | Lowest risk adult bracket |
| 65–74 | 15.44 | Lowest fatal crash involvement overall |
Separate Policy vs. Adding a Teen to an Existing Family Policy
Parents frequently wonder whether it is cheaper to buy a standalone auto policy for their teenager. In almost every scenario, purchasing an individual policy for a teen driver is significantly more expensive than adding them to an existing household policy. Standalone policies for minors do not benefit from multi-car discounts, household bundling credits, or the mature driving records of parents. Furthermore, a minor cannot legally enter into an insurance contract in many jurisdictions without adult co-signing.
By adding the teen to your current policy, the young driver benefits from your household's continuous coverage history and existing multi-vehicle rating tier. In addition, establishing prior insurance history under a parent's policy protects the teen from predatory rate tiers when they eventually purchase their own policy as an adult.
Four Proven Steps to Lower Teen Car Insurance Premiums
While you cannot change your child's age or lack of driving experience, you can implement strategic adjustments to keep household car insurance costs manageable. Apply these four proven steps to reduce your out-of-pocket expenses:
- 1
Assign the Teen to the Lowest-Risk Household Vehicle
Many insurers allow policyholders to designate which household member is the primary operator for each registered vehicle. Assigning your teen driver to an older, modest four-door sedan rather than a high-performance coupe or newer sport utility vehicle prevents heavy comprehensive and collision surcharges. Check your policy declarations page to confirm primary driver assignments.
- 2
Claim Good-Student and Driver-Education Discounts
Insurers reward young drivers who demonstrate discipline. Most insurance companies offer good-student discounts for high school and full-time college students who maintain a grade point average of 3.0 ('B' average) or higher, or who appear on the honor roll. Completing certified driver education programs also yields meaningful upfront discounts.
- 3
Increase Physical Damage Deductibles Strategically
According to the Insurance Information Institute, increasing your collision and comprehensive deductible from $200 to $500 can reduce your physical damage premium by 15% to 30%, while choosing a $1,000 deductible can cut those coverage costs by 40% or more. Setting aside an emergency reserve fund allows you to maintain higher deductibles with complete confidence.
- 4
Enroll in a Usage-Based Telematics Program
Usage-based insurance programs rely on smartphone apps or plug-in onboard diagnostic devices to track real-time driving habits, including excessive speed, hard braking, time of day, and total mileage. Safe young drivers who avoid late-night trips and harsh driving events can qualify for significant telematics discounts while simultaneously reinforcing defensive driving.
Selecting the Right Vehicle for an Inexperienced Driver
The vehicle your teenager drives plays an enormous role in determining your annual premium. High-horsepower cars, sports vehicles, and large luxury SUVs invite higher accident frequency and cost substantially more to repair after an incident. Conversely, extremely small subcompact cars offer less structural protection during multi-vehicle collisions.
The Insurance Institute for Highway Safety recommends outfitting young drivers with midsize cars, small-to-midsize SUVs, or minivans equipped with advanced crash-avoidance technology like automatic emergency braking. Vehicles earning Top Safety Pick designations offer superior structural crashworthiness and predictable handling. Choosing a model with a low vehicle symbol rating directly translates into lower collision coverage charges on your bill.
Questions & answers
When do I need to inform my insurance company about my teen driver?
You must inform your insurer as soon as your teenager earns their official, unrestricted driver's license from the state licensing agency. Most insurers do not charge an added premium while the teen holds a learner's permit, but failing to add a licensed teen can lead to denied claims or policy cancellation.
Is it cheaper to get a separate policy for a teen driver?
No. In almost all circumstances, purchasing a separate policy for a teenager costs substantially more than adding them to an existing family policy. Standalone policies lack multi-car discounts, bundling credits, and the benefit of mature household driving records.
What discounts are available specifically for young drivers?
Common discounts for young drivers include good-student discounts for maintaining a 'B' (3.0 GPA) average, driver education training discounts, distant-student discounts for teens away at college without a car, and telematics or usage-based driving discounts.
How can I check which car my teen is assigned to on my policy?
Review your policy declarations page or log into your insurance carrier's online portal. Look for the driver assignment section, which lists primary operators next to each vehicle identification number (VIN).
Terms: Age band, Inexperienced operator, Bundling (multi-policy discount), Prior insurance, Telematics (usage-based insurance)
Sources and references
Legal figures on this page (minimum limits, filing periods, statutory benefits) are checked against the primary law or the state insurance regulator listed below. Links and figures last verified Nov 2026.
- Teenagers — Insurance Institute for Highway SafetyIndependent researchTeen crash risk, graduated driver licensing research and vehicle recommendations for young drivers.
- Background on: Pay-as-you-drive auto insurance (telematics) — Insurance Information InstituteIndependent researchUsage-based and per-mile pricing models, what telematics programmes measure, and state limits on their use.
- Graduated licensing laws by state — Insurance Institute for Highway SafetyIndependent researchState-by-state learner, intermediate and full-licence ages, night-driving and passenger restrictions.
- Drivers in fatal motor vehicle crashes by age, 2023 — Insurance Information Institute (2025)Statistical dataFatal-crash involvement per 100,000 licensed drivers: 42.40 (16–20), 35.34 (21–24), 28.97 (25–34), 24.18 (35–44), 21.70 (45–54), 19.45 (55–64), 15.44 (65–74), 16.63 (75+).
- Fatality facts: Teenagers — Insurance Institute for Highway Safety (2024)Statistical dataFatal crash rate per mile driven for 16–19-year-olds is just over 3 times the rate for drivers 20 and older (2022 travel data); all-severity crash rate is over 4 times; risk is highest at 16–17.
- Facts + Statistics: Teen drivers — Insurance Information InstituteStatistical dataCrash and fatality statistics for drivers 16–19 and graduated licensing context.
- Top Safety Pick awards — Insurance Institute for Highway SafetyStatistical dataCurrent award winners; useful when choosing a vehicle for a new or young driver.
- Nine ways to lower your auto insurance costs — Insurance Information InstituteConsumer guidanceShop at least three quotes; raising a deductible from $200 to $500 can cut collision/comprehensive cost 15–30%, $1,000 can save 40%+; drop physical damage on cars worth under 10× the premium; bundling, low-mileage and good-student discounts.
Practical guidance on this page is original editorial work. Cited sources support factual statements and do not endorse this site. Dollar ranges described as typical or illustrative are editorial estimates, not figures from these sources.